Introduction: Market Access at a Price
For Bangladesh’s ready-made garment (RMG) sector, access to the United States has never been cheap, but it has now become explicitly conditional. The US–Bangladesh Agreement on Reciprocal Trade, signed on 9 February 2026, reduces headline tariff rates on Bangladeshi exports while embedding a new architecture of conditions that reshape sourcing, regulation, and long-term strategic autonomy. The agreement lowers most US tariffs on Bangladeshi goods to 19% and promises a zero-tariff pathway for a capped volume of apparel that uses US-produced cotton or man-made fiber, but ties those benefits to the amount of US textile input Bangladesh imports. In return, Bangladesh opens wide swathes of its market to US goods and accepts a set of regulatory alignments. The deal builds on and partially replaces the ad hoc reciprocal tariff regime Washington rolled out from April 2025 onward.
Here, we will evaluate whether the new tariff terms genuinely strengthen Bangladesh’s RMG competitiveness or merely postpone a deeper vulnerability within the post-LDC, geopolitically fragmented trade order.
1. What Exactly Changed? From MFN Duties to “Managed” Access
The Tariff Baseline and the 2025 Shock
Historically, Bangladeshi apparel entered the US under high MFN tariffs averaging roughly 15–17%, since garments were never included in US GSP preferences. The US suspended Bangladesh’s GSP benefits after 2013 on labor and safety grounds, and the GSP program itself lapsed in 2020; even if revived, apparel would not be covered. Thus, RMG faced full MFN rates, unlike Bangladesh’s EU access under EBA.
In 2025, Washington imposed broad reciprocal tariffs under emergency authorities. Analyses at the time placed Bangladesh’s effective apparel duty burden in the mid-30% range when the new surcharge was layered atop MFN rates. Industry briefings and media reporting converged on an effective ~36.5% for many categories, triggering buyer renegotiations and order risk.
The 2026 Agreement: A Lower 19%-With Strings
The February 2026 deal cuts the reciprocal tariff rate for Bangladesh to 19% for most goods, with conditional zero tariffs for a specified volume of textile and apparel using US inputs. The zero-tariff volume is not automatic; it scales with Bangladesh’s imports of US cotton and man-made fiber, and operational details caps, allocation rules, certificates are still being worked out.
At the same time, the White House underscored that Bangladesh will ease non-tariff barriers by accepting US standards (e.g., FDA certifications, vehicle safety), and open its market more widely to US industrial and agricultural goods, creating a reciprocal framework rather than a unilateral preference.
2. The Zero-Tariff Pathway: Preferential Access or Input-Linked Dependency?
The biggest political headline is the zero-tariff mechanism for Bangladesh’s apparel, but only when garments are made with US-origin textile inputs and within a cap that is indexed to those imports. This is a novel managed-trade design: tariff relief is contingent on Bangladesh redirecting its raw-material sourcing toward the US.
Bangladesh’s textile mills currently use a diversified cotton basket; US cotton’s share was ~10% in 2025, which BTMA suggests could rise 4–5× if the mechanism is attractive and predictable. That shift requires not just new supply contracts but also traceability and certification (e.g., via the US Cotton Trust Protocol), investment in bonded warehousing, and clarity on blends and recycled inputs issues BTMA has flagged in letters to US industry counterparts.
The result is conditional market access that tilts input demand toward American suppliers. Bangladesh gets tariff relief; US farmers and fiber producers get a captive and expanding market. The risk for Bangladesh is that input cost volatility and regulatory requirements may erode the net price advantage the zero-tariff pathway ostensibly provides.
3. Asymmetry in Market Opening and Regulatory Alignment
The agreement is not just about tariffs; it requires Bangladesh to liberalize toward US goods and recognize US standards, while the US offers a flat reciprocal rate plus a conditional carve-out for apparel. According to domestic disclosures, over 7,000 US tariff lines receive duty-free access (many immediately, others phased), while about 2,500 Bangladeshi tariff lines enjoy reciprocal duty-free treatment in the US, with apparel carved out only if US inputs are used and within a cap. This creates a broad asymmetry in market opening.
On the regulatory side, Bangladesh commits to accept US conformity assessments, FDA certifications, and US automotive standards, and to remove import restrictions on remanufactured goods. These provisions reduce non-tariff friction for US exporters and tilt future rule-making toward US regulatory templates, increasing compliance costs for Bangladeshi firms and agencies.
4. The Future Context: Legal Flux in the US and Negotiation Risk
The US trade posture is in flux. A February 2026 Supreme Court ruling curtailed the administration’s ability to impose global tariffs under emergency powers, prompting a temporary 10% surcharge under a different statute while Washington pivots to more durable legal bases (e.g., Section 301) once the temporary authority expires. For countries without activated agreements, this implies potentially higher, longer-term targeted rates. Bangladesh’s agreement is signed, but implementation steps remain; the legal and political environment in Washington could still affect the durability and scope of relief.
Meanwhile, competitors like India are negotiating parallel frameworks, and officials have publicly signaled similar zero-tariff clauses linked to US input use, which could dilute Bangladesh’s relative edge once those arrangements are finalized.
5. The Macroeconomic Effect of US Conditions: Why Prices May Rise Despite Tariff Relief
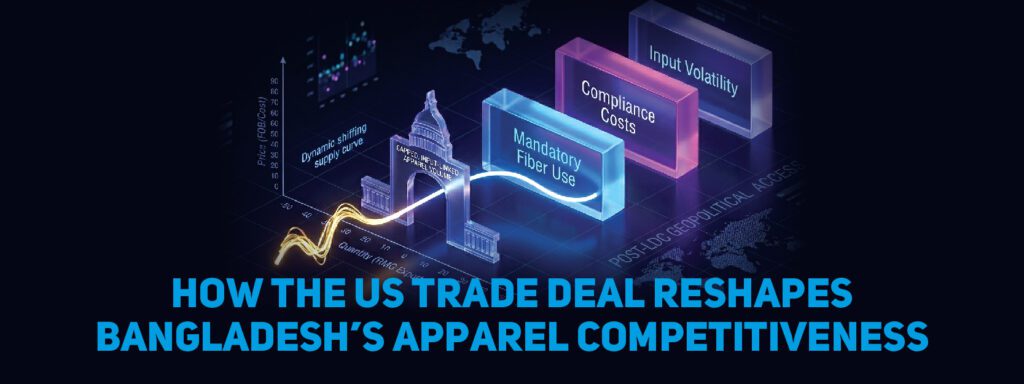
While the new deal promises lower tariffs 19% generally and zero for a capped, input-linked apparel volume the embedded conditions create counteracting forces that can push prices upward rather than down. In macroeconomic terms, this is a cost-push story: the tariff cut affects demand, but the US conditions raise production costs, shifting the industry supply curve left and putting upward pressure on prices.
Cost-Push Dynamics: The Leftward Supply Shift
- Mandatory Use of US Cotton/Man-Made Fibers: The zero-tariff mechanism requires a minimum share of US-origin textile inputs, and the cap on duty-free exports scales with Bangladesh’s imports of US inputs. BTMA notes US cotton’s ~10% baseline and expects a 4–5× increase in the near term if rules are clarified and traceability is workable. But US cotton is typically more expensive than alternatives from Africa, Brazil, or India; raising its share pushes marginal costs up at every output level. The industry supply curve shifts left, and FOB prices face renewed pressure, even as buyers demand to capture the tariff windfall.
- Compliance and Regulatory Costs: The agreement requires Bangladesh to accept US standards (FDA, vehicle safety, conformity assessment) and to reduce non-tariff barriers. Even if apparel is not subject to FDA rules directly, the broader compliance ecosystem, traceability under UFLPA, ESG auditing, documentation raises fixed and variable costs, further shifting supply left. Sector leaders have already warned that the new framework increases production and compliance costs, even as order books remain sensitive to price.
Result: With tariff reductions on the demand side but rising input and compliance costs on the supply side, equilibrium can move toward higher prices and lower quantities than a simple tariff-cut model would predict.
Market-Level Consequences: Managed Trade Outcomes
- Import Surge Dampening: By raising producer costs through input sourcing rules, the US effectively tempers import surges without resorting to overt protection. The mechanism mimics a tariff’s impact via cost-push rather than a border tax.
- Value Transfer to US Input Suppliers: The input-linkage creates a transfer to US cotton and fiber producers, which BTMA characterizes as building a “captive and expanding market” for American cotton.
- Conditionality and Leverage: The design keeps Bangladesh dependent on compliance channels labor, environment, traceability providing Washington with ongoing leverage over access.
Bottom line: The deal reduces tariffs but increases costs, leading to a leftward supply shift that raises equilibrium prices. The US gains supply chain control and input-market expansion; Bangladesh bears higher production and administrative costs within a managed-trade equilibrium.
6. Labor, GSP, and Reputation: Necessary but Insufficient
Bangladesh’s apparel is excluded from US GSP, and the program itself has been dormant since 2020. US messages have been consistent: improving labor rights and safety could support broader trade benefits and reputational standing, but even a GSP revival would not grant duty-free treatment for garments. Still, progress on labor reforms remains vital to reduce non-tariff risks (e.g., detentions, audits), sustain buyer confidence, and defend against advocacy-driven restrictions.
7. Strategic Choices for Bangladesh: Turning Access into Advantage
To convert conditional access into durable competitiveness, Bangladesh should pursue a four-pillar strategy:
- Upgrade the product mix: Move beyond cotton-heavy basics into MMF-rich, performance, and fashion-forward categories where tariff sensitivity is lower and value-addition is higher. This cushions cost-push shocks from input conditions and increases pricing power. (Competitive context: rivals are negotiating similar frameworks; Bangladesh must keep moving up the value chain.)
- Rewire the input base intelligently: If using US cotton to unlock zero-duty quotas, negotiate stable, multi-year pricing and logistics with US suppliers; invest in traceability infrastructure (digital chain-of-custody, certification) to reduce per-unit compliance costs; clarify blend/recycle rules to avoid disqualification and stranded inventories.
- Institutionalize compliance at scale: Treat UFLPA-grade traceability, ESG auditing, and data integrity as public-good infrastructure (shared registries, training, and verified platforms) rather than firm-by-firm fixes. This reduces fixed costs for SMEs and helps sustain market access under stricter US scrutiny.
- Negotiate for predictability, not just rates: Press for transparent cap formulas, carry-forward provisions, and clear certification rules in the zero-tariff mechanism. Seek mutual recognition that avoids duplicative testing and codify review timelines so firms can book capacity with confidence. The legal flux in Washington (shift from emergency tariffs to Section 301 pathways) makes predictability as valuable as numeric rates.
Conclusion: Access Secured, Autonomy Deferred
The US–Bangladesh trade deal stabilizes access and removes the immediate shock of 2025’s elevated effective duties. Yet tariff relief is conditional and capped, tethered to costlier input sourcing and regulatory alignment that raise production and compliance costs. In macroeconomic terms, the agreement shifts the supply curve left, producing cost-push price pressure that can blunt the headline benefit of lower tariffs.
If Bangladesh uses this window to upgrade products, professionalize compliance, and lock in predictable rules, it can convert managed access into resilient competitiveness. If not, the deal risks becoming a ceiling on ambition a framework that grants entry but governs terms of participation so tightly that the country’s value capture remains constrained.
Sources
- White House joint statement (Feb 9, 2026); USTR letter/text
- DW report on the 19% rate & zero-tariff mechanism; Economic Times summary; Hindustan Times
- The Business Standard—duty-free line counts & BTMA operational asks; Financial Express—BGMEA’s 36.5% effective rate context
- The Daily Star analysis of Supreme Court ruling & tariff pivot
- Business Standard on India’s negotiations & zero-tariff clauses; CCFGroup note on parity for Indian textiles
Author: Yousuf Abdullah Pavel