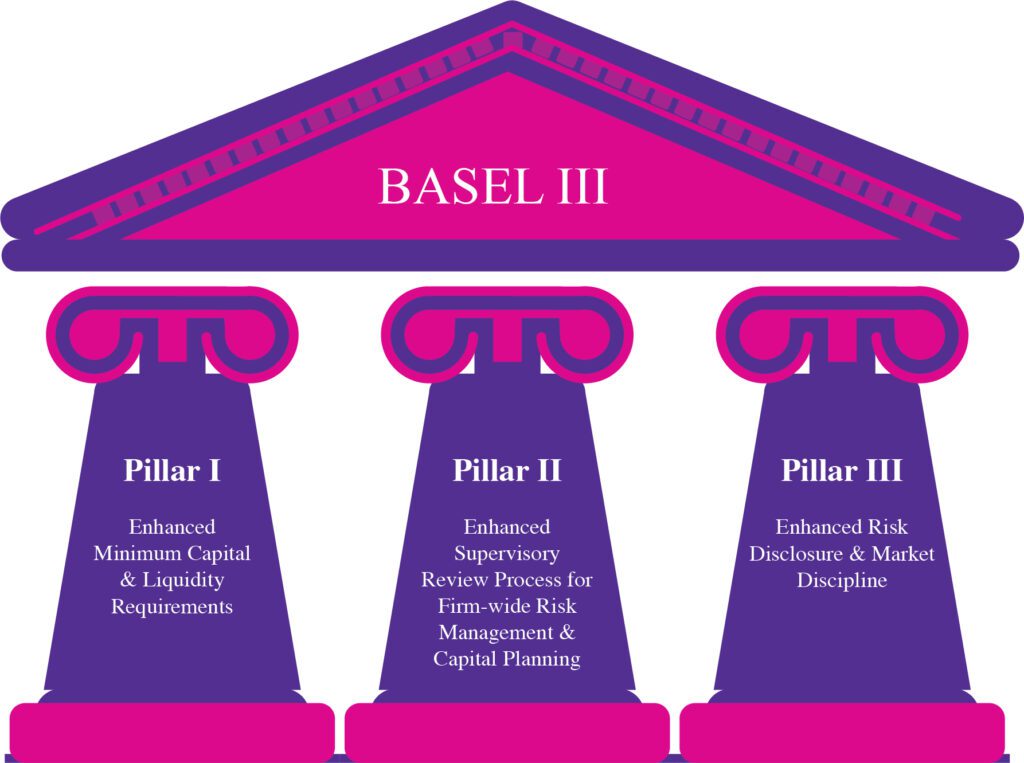
Global banking regulation once aimed for unity. After the 2008 crisis, countries rallied around common principles to reduce systemic risk and improve oversight. Basel III was designed to fix capital shortfalls, tighten liquidity standards, and improve the resilience of banks operating across borders.
The ambition was to ensure that never again should the collapse of one institution trigger a global meltdown.
But that vision is now in question. Coordination has eroded. Political priorities are diverging. And the fractures in the system, once considered temporary, are beginning to look permanent.
Post-Pandemic: A Quiet Rewriting of Commitments
When COVID-19 hit, regulators acted fast to cope with the new normal. They eased capital rules, delayed stress tests, and encouraged banks to keep lending. Those adjustments were meant to be temporary. Yet many remain in place, repackaged as flexibility or national discretion. What was once a global consensus is now a policy patchwork.
This shift is subtle but important. While most jurisdictions claim to comply with Basel III, the actual implementation tells a different story. Some regulators recalibrate risk weights. Others exempt certain exposures. And some delay rules altogether, citing domestic challenges. It creates the illusion of harmony, even as banks face different standards in practice.
The Basel III “endgame” negotiations, meant to finalize post-crisis reforms, have become politically sensitive. The United States, for example, introduced revised capital requirements in 2023. However, European institutions have pushed back, citing fears over competitiveness. Japan, meanwhile, has taken a lighter approach to avoid pressuring local lenders. Each decision may be defensible in isolation, but collectively, they chip away at uniformity.
Financial Nationalism is Now Standard Practice
The global financial landscape has changed now. Governments have become more protective of their banks. Regulatory divergence is no longer the exception. It is now the default.
This trend does not always announce itself. Instead, it appears as “tailored supervision” or “national alignment.” The terminology may sound cooperative, but the intent is often to insulate local institutions from global pressure.
Recent moves underscore this trend. In 2023, the United Kingdom unveiled its Financial Services and Markets Act. The legislation prioritises competitiveness and gives regulators more room to adjust standards for domestic needs. Across the Atlantic, US regulators are engaged in a heated debate over whether their Basel III revisions go too far. Banking groups argue that higher capital charges will curb lending and hurt growth.
These decisions are not just technical adjustments. They reflect a political shift. Policymakers are more concerned with local credit supply than with international consistency. As a result, the idea of a single global rulebook is steadily losing traction.
Supervisory Coordination Is Fraying
Global banks still operate across jurisdictions. But the supervisory relationships that once provided some stability are starting to wear thin. Cross-border cooperation, while still active, is now more cautious.
The 2023 failure of Credit Suisse highlighted this fragility. Swiss regulators, in a bid to preserve confidence, wiped out subordinated bondholders while protecting shareholders during the bank’s forced sale. This reversed the traditional order of claims and caught European authorities off guard.
The world saw an immediate fallout. Investors questioned whether they could rely on established norms during crisis resolution. Regulatory coordination had failed at a critical moment.
This episode was not an outlier because it revealed how quickly national decisions can disrupt global expectations. And it demonstrated that even within relatively aligned systems, like Europe, crisis management strategies can sharply diverge.
The G20 Is Less Influential Than It Once Was
The G20 once played a leading role in driving financial reform. In the aftermath of the global financial crisis, it supported the Basel Committee, endorsed financial stability goals, and pressured lagging jurisdictions to catch up. That influence has diminished.
Tensions among key members have reduced the group’s ability to deliver strong commitments. Sanctions, strategic competition, and political mistrust have weakened the trust needed for meaningful cooperation.
Russia’s sidelining and China’s limited transparency have added complexity. Meanwhile, advanced economies are increasingly focused on domestic vulnerabilities. With fewer shared incentives, collective action has become harder to achieve.
Without G20 pressure, national regulators feel less compelled to follow through. The global consensus is no longer enforced by political will. It relies instead on voluntary alignment, which is proving unreliable.
Digital Finance Is Escaping Traditional Oversight
Regulatory gaps are widening in emerging areas of finance. Digital assets, stablecoins, and fintech platforms are developing faster than rulebooks can adapt. Inconsistent treatment across jurisdictions creates risks that are harder to manage.
Take stablecoins for example. In some countries, they are treated as e-money. In others, they fall under securities law. Some regulators impose capital requirements. Others ban them outright. This lack of clarity invites regulatory arbitrage, where firms seek out the most lenient environments. It also increases the likelihood of cross-border disputes when things go wrong.
Global coordination on digital finance has begun, but progress remains slow. In 2023, the Financial Stability Board issued updated recommendations on crypto-asset supervision. Yet implementation remains uneven. While the European Union has passed a comprehensive framework under MiCA, other regions are still debating their approach. Without alignment, the same risks that led to past financial crises could reappear in digital form.
Central Banks Are Now Moving in Different Directions
For much of the past decade, central banks worked in concert. Interest rates were low. Quantitative easing was common. Regulatory tweaks were coordinated. That era has ended.
In 2023, central banks faced very different realities. The Federal Reserve remained committed to fighting inflation through higher rates. The European Central Bank struggled to balance inflation with economic fragility. Meanwhile, central banks in Asia had to defend their currencies against capital outflows while maintaining domestic growth.
These divergent paths impact bank supervision. Monetary tightening affects credit risk, funding costs, and capital buffers. If supervisors do not share a common outlook, banks face conflicting guidance. That makes planning more difficult and could amplify stress in the next downturn.
What Might Survive
While full regulatory convergence appears unlikely, some forms of coordination may still endure. Areas like cyber risk, anti-money laundering, and systemic stress testing are less politically charged. These topics lend themselves to technical cooperation even when broader alignment falters.
Information sharing, peer reviews, and crisis simulation exercises can continue to support stability. And large international banks may still apply internal risk frameworks that exceed local minimums. These measures offer some resilience, even in a fractured system.
However, this approach has limits. Financial shocks could spread unpredictably without shared rules on capital, liquidity, and resolution. Global financial safety relies on more than goodwill. It depends on enforceable standards and credible enforcement.
The Cost of Fragmentation
Regulatory divergence may seem manageable in calm periods. But during stress, gaps become dangerous. A crisis in one jurisdiction can quickly spill into others. If the responses are not aligned, confidence evaporates.
Cross-border banking thrives on predictability. When banks face inconsistent rules, they reduce exposure or pull back from certain markets. That reduces efficiency and raises the cost of capital. In the long run, it may also limit financial inclusion, particularly in emerging economies that depend on foreign investment.
The world is not returning to the pre-crisis model of complete regulatory independence. But neither is it moving toward full harmonization. Instead, it is settling into a fragmented system where national preferences dominate and global rules are increasingly optional.
Regulatory Disunity Might Be Strategic
It’s easy to assume that fragmented banking rules are a symptom of geopolitical instability. But there’s another angle that deserves attention. For many mid-sized and emerging economies, deviation from global standards is not a failure. It is a strategy.
By adjusting the pace of Basel III implementation or redefining supervisory thresholds, regulators can create more flexible environments to support domestic credit growth. This isn’t just about falling behind. It reflects a desire to compete, not conform. Countries with different growth profiles and financial systems may see strict international compliance as a limitation rather than a strength.
This shift challenges the idea that global harmony is always ideal. When regulators in Jakarta or Lagos make different decisions than those in Frankfurt or New York, they may be responding to completely different risks and opportunities.
The concern isn’t the variation itself, but the lack of a shared platform where flexible approaches can still align with coordinated oversight. Without that structure, divergence becomes the default.
Three Plausible Futures for Global Banking Regulation
Global banking coordination is no longer guaranteed. Based on the current trajectory, three possible futures are beginning to emerge.
- Regionalization Becomes Standard
Global rules lose ground to regional ones. Groups like the European Union, ASEAN, and African Union set up frameworks tailored to local financial conditions. Basel standards remain a reference point, but compliance is selective.
- Private-Led Standardization Takes Over
Multinational banks and major audit firms create their own cross-border benchmarks to manage internal risk. These unofficial standards start to influence market behavior more than international accords. It is not ideal, but it fills the gap left by regulatory drift.
- Crisis-Driven Coordination Returns
Only a major financial disruption is strong enough to pull regulators back into alignment. If a cross-border fintech collapse or sovereign default occurs, countries may respond by setting up rapid, situation-specific rules. This reactive approach becomes the new form of global engagement.
None of these futures guarantees better outcomes. But they each reflect where the world could realistically head next. Hoping for a full revival of global consensus may be less productive than preparing for a world of parallel play, not synchronized movement.
Author: Rafsan Ahmed