Bangladesh’s rising debt pressure is often discussed through headline numbers billions of dollars in repayments, large infrastructure loans, and tightening fiscal space. Yet debt figures alone do not explain why the pressure is increasing now, after decades in which Bangladesh was widely considered a low-risk borrower.
In the 54 years since independence, Bangladesh has paid around $40 billion in external debt servicing. What makes the current moment unusual is that nearly two-thirds of that amount must be repaid within just five years, between the current fiscal year. According to the Economic Relations Division, the country will need to pay almost $26 billion in external debt servicing during this period, based solely on loans contracted up to FY25.
From a macroeconomic perspective, this is not simply a story about rising debt. It is a story about timing, growth, foreign currency earnings, and fiscal capacity.
Debt and the Intertemporal Budget Constraint
“Borrowing Today, Paying Tomorrow”
Government borrowing through the idea of an intertemporal budget constraint a simple concept that compares today’s spending with tomorrow’s repayment ability.
In plain terms, a country can borrow today only if it expects future income to cover tomorrow’s obligations.
Over the past decade, Bangladesh borrowed heavily to finance large infrastructure projects such as the Rooppur Nuclear Power Plant, the Dhaka Metro Rail, the Karnaphuli Tunnel, the Padma Rail Link, airport expansion, and several energy-related facilities. During the Covid-19 period, additional borrowing was used to stabilize public finances.
These borrowing decisions were based on the expectation that future growth would comfortably absorb future repayments. The difficulty is not that borrowing occurred, but that many of these loans are now reaching repayment simultaneously as grace periods expire.
As a result, debt servicing obligations are rising sharply within a short time frame, creating pressure even without any sudden increase in borrowing.
Growth-Led Debt Sustainability: When Growth Arrives Late
“Some of the major projects financed with foreign loans are yet to generate returns, while repayments have already begun. This mismatch between repayment schedules and economic returns is increasing debt stress.” (The Business Standard, 2026)
A key macroeconomic rule of debt sustainability is that borrowing remains safe when economic growth exceeds the interest rate on debt. Growth expands national income, making fixed repayments easier to manage.
Bangladesh’s infrastructure-driven borrowing strategy fits this logic. Large projects were expected to:
- Improve productivity
- Reduce logistical bottlenecks
- Support export growth
However, macroeconomics also stresses timing. Growth benefits must arrive before or alongside repayment obligations.
Delays have created a gap between repayment schedules and economic returns. Some projects remain underutilized or face operational bottlenecks, meaning debt servicing has begun while growth dividends are still incomplete. This mismatch intensifies repayment pressure even if projects are viable in the long term.
The Foreign Currency Constraint: When Debt Becomes a Dollar Problem
The pressure from external debt has also intensified because Bangladesh’s macroeconomic buffers have weakened in recent years due to repeated global shocks. The Covid-19 pandemic, followed by the Russia-Ukraine war and global monetary tightening, disrupted export demand, raised energy import costs, and slowed global labor markets that support remittance inflows. From a macroeconomic perspective, these shocks matter because they reduce a country’s ability to adjust smoothly to rising repayment obligations. When foreign exchange earnings slow at the same time that external debt servicing accelerates, even a country with moderate debt ratios can experience repayment stress. This explains why Bangladesh’s debt challenge has emerged not from excess borrowing alone, but from a compressed adjustment window shaped by global conditions beyond domestic control.
External debt is repaid not in taka but in foreign currency, primarily US dollars. This brings in the macroeconomic concept of the balance-of-payments constraint.
A country earns foreign currency through:
- Exports
- Remittances
- Foreign investment
Bangladesh’s external earnings have grown, but remain vulnerable to global shocks and structural concentration. Export diversification is limited, remittances depend on global labor markets, and capital flows are sensitive to confidence and energy prices.
Debt repayments, however, are contractually fixed.
This makes rising debt servicing a foreign-exchange management issue, not just a fiscal one. Even if annual repayments appear manageable on average, periods of foreign-currency stress can significantly amplify pressure.
Fiscal Capacity: Low Revenue, High Fixed Payments
Another layer of debt pressure emerges from the interaction between external obligations and rising domestic borrowing. As external repayments increase, governments often rely more heavily on domestic sources to manage liquidity and finance budgetary needs. From a macroeconomic perspective, this can raise overall interest costs and tighten financial conditions within the economy. Higher domestic borrowing absorbs bank liquidity, increases yields on government securities, and raises debt-servicing costs even further. While this process does not trigger an immediate crisis, it gradually reduces fiscal flexibility and increases vulnerability to shocks. In Bangladesh’s case, rising domestic interest payments mean that external debt pressure does not remain confined to foreign obligations alone, it spills over into the broader fiscal system.
Debt servicing ultimately passes through the government budget. Here, Bangladesh’s low tax-to-GDP ratio becomes a critical macroeconomic constraint.
With limited revenue mobilization, rising debt payments absorb a larger share of public resources, reducing space for development and social expenditure. Economists describe this as fiscal crowding out, where debt obligations limit policy flexibility.
In such a context, rising repayments feel heavier not because debt is excessive, but because revenue growth lags behind financial commitments.
Debt Composition Matters More Than the Headline Number
A country cannot borrow its way out of a repayment problem indefinitely. When existing debt servicing rises sharply, new borrowing increasingly serves to manage liquidity rather than finance growth-enhancing investment. This shifts the role of debt from development support to short-term adjustment, reducing its effectiveness as a policy tool. In such circumstances, reliance on additional borrowing may temporarily ease pressure, but it also postpones necessary structural corrections, such as export diversification, revenue reform, and project efficiency. Bangladesh’s current debt stress reflects this transition point, where sustainability depends less on access to new loans and more on restoring alignment between repayment capacity and economic fundamentals.
All debt is not treated equally. Risk depends on terms, not just totals:
- Interest rates
- Grace periods
- Repayment horizons
- Currency denomination
Bangladesh’s recent borrowing increasingly reflects shorter-grace and harder-term loans, which compress repayment obligations even when the overall debt stock remains moderate.
This change in debt composition explains why pressure is rising faster than anticipated.
Economist’s also stresses the role of expectations and market perception in debt sustainability. As debt servicing rises, investors and lenders focus less on headline debt ratios and more on repayment capacity, foreign exchange availability, and policy credibility. This shift explains why financing conditions tend to tighten even when debt-to-GDP indicators remain stable. In Bangladesh’s case, rising repayment schedules have increased scrutiny from development partners and multilateral institutions, leading to greater emphasis on revenue reforms, cautious borrowing, and external balance management. The adjustment pressure now facing the economy is therefore not the result of panic or market collapse, but of a gradual reassessment of risk as repayment obligations become more front-loaded.
Is Bangladesh Headed Toward a Crisis?
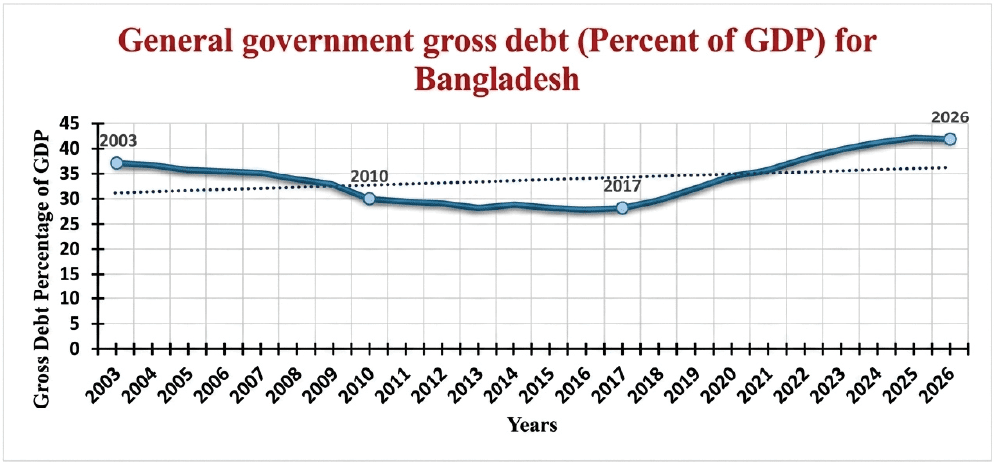
(International Monetary Fund [IMF], n.d.)
Debt-to-GDP is the standard indicator used to assess sustainability. The time-series trend shows that Bangladesh’s overall debt burden remains moderate by international standards and well below levels associated with sovereign crisis.
This visual evidence is crucial. It confirms that Bangladesh is not facing a debt crisis driven by excessive borrowing. Instead, it is experiencing debt stress driven by repayment timing and structure.
Why the Warning Signs Emerged Late
Economic decisions are influenced by political incentives. Large infrastructure projects deliver visible benefits early, while debt servicing costs emerge later and more quietly.
This creates a tendency to underestimate future repayment pressure, especially when growth assumptions appear plausible at the time of borrowing. Bangladesh’s experience reflects this classic political-economy pattern.
Conclusion
Bangladesh’s rising debt pressure is best understood through macroeconomic timing.
- Borrowing assumed future growth.
- Growth has arrived more slowly.
- Repayments are arriving all at once.
The challenge is not excessive debt, but misalignment between repayment schedules, growth realization, foreign-currency earnings, and fiscal capacity. Recognizing this distinction is crucial, because early adjustment is always less costly than emergency correction.
The lesson is simple: Debt sustainability depends not only on how much a country borrows, but when it must pay and whether growth keeps pace.